DebiCheck Mandate: What Your Bank Is Asking You to Approve, and When to Decline
A DebiCheck request is your bank asking you to confirm a new debit order once, before the first collection. What to check, how long you have to answer, and why declining is not the same as cancelling.
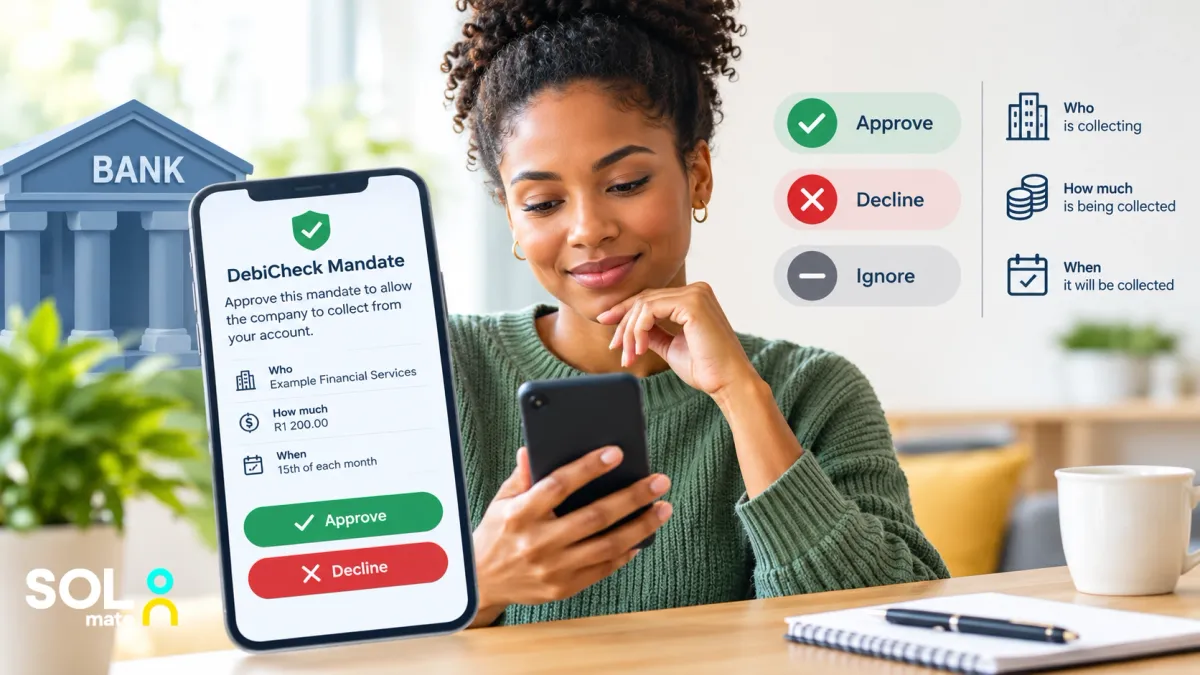
DebiCheck is a type of debit order that you confirm with your own bank, once, before a company can start collecting from your account. The message asking you to "approve a DebiCheck mandate" is that confirmation. The mandate is the permission itself: who may collect, how much and on which date. DebiCheck is not a company, not a subscription and not a charge on its own.
Approve it if you have just signed up for something and the details match what you agreed to. Decline it if you don't recognise it. Either way, answer it, because ignoring the request does not make the contract behind it go away.
Why Your Bank Is Suddenly Asking
For years a company needed only your signature on a form, or a recorded "yes" on a phone call, to load a debit order. Your bank was never asked, and debit orders nobody had agreed to became common. The Reserve Bank asked the payments industry for a fix. Since 1 May 2021, every new or renegotiated early debit order (the kind that runs in the morning, right after salaries land) has had to be set up in the DebiCheck system.
Your bank keeps an electronic copy of what you approved and checks every collection against it. A collection that matches goes through. One that doesn't is rejected. You confirm once, at the start of the contract, and are asked again only if the amount or the date changes.
Three Things to Read Before You Approve
- Who is collecting. It should be the company you have just dealt with.
- How much. It should be the instalment in your contract. For a small loan, the law caps what a lender may charge.
- When. The collection date you agreed to, which works best just after your pay arrives.
Then ask whether the timing makes sense. A genuine request shows up while you are taking out a loan, a policy or a contract, or shortly after. One that arrives out of nowhere deserves a no.
The request comes through your bank's own channels. Depending on the bank, that is the app, a USSD prompt, internet banking, an ATM, a branch, or your card and PIN. The Payments Association of South Africa (PASA) is clear about the rest: banks will never send a link or ask for your card PIN, password or personal details to approve a DebiCheck. A message that does is phishing.
Who Is Writing This
SOLmate is a South African money app, not a bank. An account costs R10.00 a month, or R29.00 a month with a debit card, and money coming in by EFT is free. Sign-up takes about three minutes in the app, with an SA ID, a foreign passport or an asylum seeker permit and no proof of address.
How Long You Have to Answer
That depends on how the company sent the request, and the company should tell you which kind it is. An immediate request has to be answered within 120 seconds, usually while you are still on the call or at the counter. Others stay open until the end of the day, or the end of the next business day. After that the request lapses.
All of this relies on your bank having your current cellphone number. If it doesn't, the request may never reach you.
Approve, Decline or Ignore: What Each One Does
| You | The debit order | The contract |
|---|---|---|
| Approve | Your bank records the mandate. Collections that match it go through, and your bank will not reverse them later. | Runs as signed. |
| Decline | No DebiCheck is set up. The company may still collect on a registered mandate, a debit order you did not authenticate and can dispute within 60 calendar days. | Still stands if you signed it. A lender may stop the application at this point. |
| Ignore | The request lapses. The result is the same as declining. | Still stands. |
The second row is the one that surprises people. Declining a mandate is not cancelling a contract. Nedbank's DebiCheck FAQ, for one, describes a registered mandate being created when a request is declined or goes unanswered, and says its personal loan application cannot continue if you decline. PASA's advice points the same way: don't ignore the request, and take any cancellation to the company, because your bank can't end a contract for you.
If you never signed anything, decline and tell your bank. If money leaves your account anyway, you have 60 calendar days to dispute it, and our guide to reversing a debit order covers how. It is also worth pulling a free credit report to see whether an account has been opened in your name.
After You Have Approved
You can ask your bank to suspend a DebiCheck mandate, which blocks future collections. The contract carries on, so the instalments stay owed until you cancel with the company.
If the account is short on the collection date, a DebiCheck debit order can track the account for up to ten days and collect when money comes in. An unpaid debit order can also earn you a penalty, often one of the bigger fees on a bank's price list. If the date simply falls before payday, ask the company to move it. A new date can mean a new request to approve.
Where SOLmate Fits
If you have a SOLmate Cash Advance, the repayment comes out of your SOLmate wallet automatically on the due date shown in the app. A three-day grace period follows before daily penalty charges begin, so keep the wallet funded for that date.
Subject to credit assessment · FSP 52248 · NCRCP16037
Sources: PASA, Debit Order FAQ (what you confirm, response times, suspension, tracking, phishing warning), PASA on debit order types, South African Reserve Bank media release of 28 April 2021, Nedbank DebiCheck FAQ, SOLmate fees, SOLmate Cash Advance help page. Bank procedures are quoted from public pages as checked on 12 October 2026 and can change; your bank's current terms decide. Facts about SOLmate were checked against SOLmate product pages on 12 October 2026.
SOLmate is not a bank. SOLmate (SOL Ecosystem (Pty) Ltd) is an authorised financial services provider (FSP No. 52248) and registered credit provider (NCRCP16037). This article is general information, not financial or legal advice.